How to Build Financial Stability Without Making Debt the Only Job Your Money Has
One of the biggest mistakes I see people make with money is actually a very understandable one.
They decide they are finally going to get serious about their debt.
So they throw every extra dollar they have at it.
They pay down the credit card. They make an extra payment on the car. They send everything possible toward whatever balance is bothering them most.
And for a little while, they feel fantastic.
Then the water heater breaks.
The car needs four new tires.
The dog needs emergency care.
A family member needs help.
Suddenly, there is no cash available for the unexpected expense because every extra dollar went toward debt.
So what happens?
Out comes the credit card.
Again.
The person feels defeated because they were doing everything “right,” yet somehow they ended up back where they started.
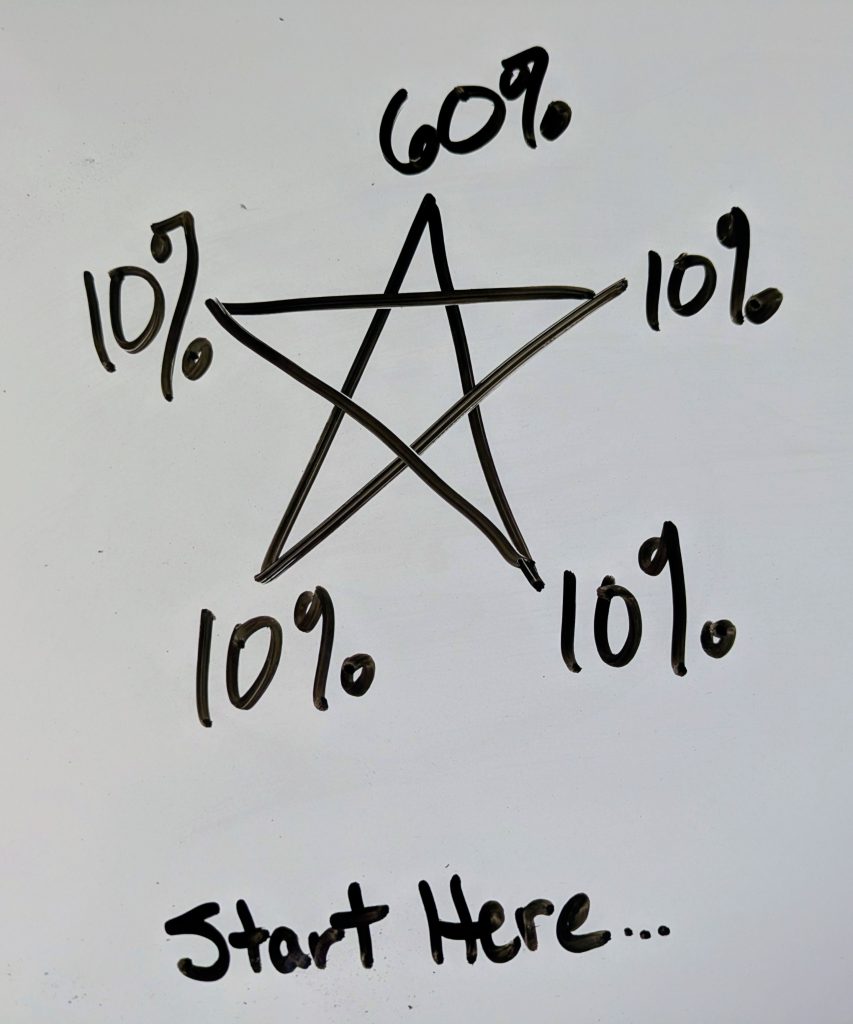
This is one of the reasons I began teaching the 60/40 Rule of Money Management many years ago.
The percentages and the way I describe the system have evolved over time, but the central idea has remained the same:
Do not make debt repayment the only job your money has.
You need to build the floor underneath you at the same time.
What the 60/40 Rule Means Today
The modern version of the 60/40 Rule is very simple:
60% supports your life.
40% builds your financial stability.
That 60% is the money supporting the life you are living now: housing, food, transportation, utilities, insurance, and the ordinary expenses required to keep your household operating.
The remaining 40% has different work to do.
Depending on where you are in life, that money may be directed toward:
building emergency savings,
reducing debt,
investing for retirement and long-term growth,
creating additional income,
giving,
or funding something you are creating for your future.
The exact percentages inside that 40% will change.
They should.
A 27-year-old starting a career has different needs than a 62-year-old preparing for retirement.
A person with $25,000 in credit-card debt has different priorities than someone whose debt is paid off but has no retirement savings.
Someone building a business has different needs than someone working a salaried job.
The 60/40 Rule is a structure, not a rigid formula.
Its purpose is to remind you that your money has more than one job.
Your Financial Life Needs a Floor (read: Foundation!)
This idea is central to Revenue Without Rush.
Before you build something new, you need somewhere solid to stand.
That is your financial floor.
When there is no savings, every unexpected expense becomes an emergency.
When every extra dollar goes toward debt, there is nothing available to absorb ordinary life.
When there is no money being invested for the future, the present is quietly borrowing from the person you will eventually become.
And when you are financially frightened, decisions that should be thoughtful suddenly become urgent.
You stay in a job because you are afraid you cannot leave.
You accept work you do not really want because you need the money immediately.
You rush a business idea.
You say yes when you really want to say no.
You make decisions from fear rather than choice.
Building a financial floor does not mean becoming wealthy overnight.
It means steadily creating enough stability that your next decision does not have to be made with your back against the wall.
Start With the Money That Is Easiest to Change
If you are currently using nearly everything you earn just to run your household, please do not read “60/40” and immediately decide that you are doing money wrong.
That completely misses the point.
Start where you are.
One of the easiest ways I have taught this principle over the years is to begin with money that is outside your normal paycheck.
That might include:
a bonus,
a tax refund,
birthday or holiday money,
a rebate,
income from a side project,
money from selling something you no longer need,
an unexpected commission,
or even the small amounts of money that accumulate when you begin paying attention.
Instead of automatically spending all of that money or throwing all of it toward debt, practice giving the money multiple jobs.
You are learning a system.
That matters more than achieving a perfect percentage on Day One.
What Does the 40% Actually Do?
Think of the 40% as the portion of your money deliberately working on behalf of your future.
You may divide it among several jobs.
Safety
This is cash you can access when life happens.
Emergency savings.
Cash reserves.
Money that keeps a flat tire from becoming a credit-card balance.
Debt Reduction
Yes, debt still gets paid down.
Absolutely.
But debt repayment is now working alongside savings rather than consuming every available dollar.
The goal is to stop creating the very conditions that force you back into debt.
Retirement and Growth
Some of your money needs to be working for the person you will be ten, twenty, or thirty years from now.
That might mean a workplace retirement account, IRA, HSA, brokerage account, or another appropriate investment vehicle.
You do not need to become an investment expert before you begin learning how to give your future self some support.
Income
Eventually, some of your assets can begin creating income of their own.
That is an important transition because your time should not have to produce every dollar that enters your life.
Creation
This is one of my favorite categories.
Creation money builds assets that did not exist before.
A business.
A book.
Intellectual property.
Education.
A product.
A body of work.
Something you are creating today that may support you tomorrow.
Giving
Giving has always been part of my own financial life.
For some people that means religious giving. For others it means charities, community organizations, family support, mutual aid, or causes they believe in.
How you give is deeply personal.
The point is to make it intentional rather than accidental.
An Example
Suppose you receive an unexpected $1,000.
Under the 60/40 structure, you might decide:
$600 supports your present life.
Perhaps you catch up on an expense, replace something that needs replacing, or simply give yourself a little additional breathing room.
The other $400 works on your financial stability.
You might put:
$150 into emergency savings.
$150 toward a credit-card balance.
$50 into an investment account.
$50 toward something you are creating or a cause you support.
Someone else may divide that $400 completely differently.
That is fine.
The magic is not hiding inside a precise allocation.
The power is in the habit:
Some money supports today. Some money deliberately builds tomorrow.
Why This Feels Different
There is a psychological change that begins to happen when you use money this way.
You can watch debt decrease while savings increase.
That matters.
Instead of looking at your finances and seeing only what you owe, you begin seeing something you own.
Instead of every surprise creating panic, you gradually create a reserve.
Instead of believing that the only way to improve your finances is deprivation, you begin experiencing financial progress in several directions at once.
This is important because money management is not merely mathematics.
It is behavior.
It is emotion.
It is habit.
And it is trust.
If your financial plan constantly makes you feel punished, deprived, frightened, or ashamed, you are going to have a difficult time staying with it.
I would rather help you build a system you can live with for decades.
You Are Allowed to Adjust the Percentages
There will be seasons when 60/40 is not realistic.
There may be a period when housing expenses are unusually high.
You may be caring for a family member.
You may be recovering from a financial setback.
You may have an opportunity to eliminate a high-interest debt much faster.
You may temporarily need a larger emergency reserve.
Adjust.
The point of the 60/40 Rule is not obedience to a spreadsheet.
The point is to keep asking:
Is all of my money being consumed by today, or is some of it deliberately building tomorrow?
That question will tell you far more than whether you achieved exactly 40%.
The Goal Is Financial Choice
Ultimately, this is not about becoming better at budgeting.
It is about increasing your choices.
Savings gives you choices.
Reducing debt gives you choices.
Investments give you choices.
Creating additional income gives you choices.
Owning assets gives you choices.
And slowly, those choices begin changing the way you move through your life.
That is why financial footing comes first in Revenue Without Rush.
Before you decide what comes next, build yourself somewhere solid to stand.
You do not need to rush.
You do not need to fix everything this month.
And you certainly do not need to shame yourself over the decisions that brought you here.
Give your money more than one job.
Support the life you are living.
Build the life you are becoming.
And keep going.
Listen & Watch
The 60/40 Principle — The Practical Mystic Show
A conversation about the original 60/40 framework and learning to give your money several jobs.
Continue the Journey…
If debt is currently the loudest issue in your financial life, start with Ditch Your Debt While Banking Bucks.
And if you are working through the Revenue Without Rush framework, this teaching belongs in Level 1: Financial Footing—building the floor that allows everything else to become possible.
This material is educational and is not individualized financial, investment, tax, or legal advice.
This article is part of Revenue Without Rush — Level 1: Financial Footing.
If you’re ready to build a stronger financial floor without shame, pressure, or rushing, explore Revenue Without Rush and see where you fit.