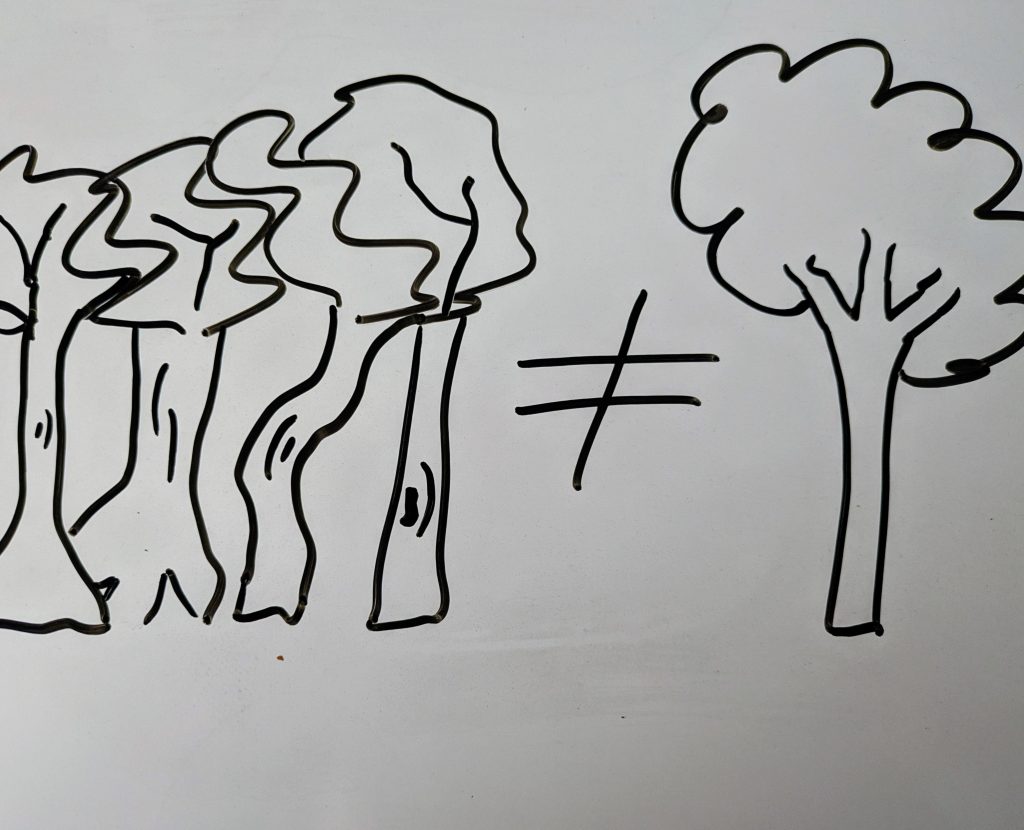
Investing: What Do I Do Now?
A Plain-English Beginning for People Who Know They Should Invest but Aren’t Quite Sure What That Means
There is a moment in almost every financial conversation when someone says:
“Okay. I understand saving. But investing? What am I actually supposed to do?”
Good question.
Because investing has an entire language attached to it.
Stocks.
Bonds.
Mutual funds.
ETFs.
Brokerage accounts.
IRAs.
Asset allocation.
Diversification.
Risk tolerance.
Expense ratios.
Dividends.
Capital gains.
Good grief.
It is no wonder perfectly intelligent people decide they will figure all of that out later.
So let’s remove some of the mystery.
You do not need to become a stock-market expert.
You do not need to watch financial television every afternoon.
You do not need to know which company is going to become the next spectacular success.
You simply need to understand what investing is supposed to do in your financial life.
Then you can learn one piece at a time.
Saving and Investing Have Different Jobs
Saving and investing are related, but they are not the same thing.
Savings is primarily about availability and stability.
That is the money you may need relatively soon.
Your emergency reserve.
Money for a planned expense.
Cash you need available if the car breaks down, the furnace dies, or your income changes.
You usually do not want that money bouncing around dramatically in value right before you need it.
Investing has a different job.
Investing means putting money into assets with the expectation that they may grow in value or produce income over time.
The important phrase there is:
over time.
Investments can go up.
They can go down.
Sometimes they go down rather enthusiastically.
That is why money you may need next month generally has a different job from money you are building for ten, twenty, or thirty years from now.
Your emergency fund and your retirement money should not necessarily be doing the same thing.
First Ask: When Will I Need This Money?
Before you ask:
“What should I invest in?”
ask:
“When am I likely to need this money?”
This is your time horizon.
If you are saving for something you expect to buy next year, you probably think about that money differently from money intended for retirement thirty years from now.
The longer the time available, the more opportunity you may have to weather the normal ups and downs of investments.
The shorter the time, the more important stability may become.
There is no universal investment that is automatically appropriate for everyone.
The destination matters.
Once again, we are navigating.
Where are you going?
And how long do you have to get there?
Then Ask: How Much Movement Can I Tolerate?
This is where people start talking about risk tolerance.
Risk tolerance means more than saying:
“I’m comfortable with risk.”
It is very easy to feel comfortable with investment risk when everything is going up.
The more useful question is:
What happens to me when the value drops?
Do you immediately want to sell everything?
Do you lose sleep?
Do you start checking the account six times a day?
Or can you look at a long-term investment, understand that markets move, and leave the plan alone?
There is no medal for accepting more risk than you can emotionally or financially handle.
Your investment plan has to be one you can actually live with.
A mathematically perfect plan that you abandon every time the market scares you is not particularly useful.
Risk and Return Travel Together
One of the first lessons to understand about investing is that there is no reliable way to separate potential return from risk.
Investments with greater potential returns generally involve greater uncertainty.
That does not mean:
High risk equals high reward.
Sometimes high risk equals losing money.
It means there is usually a trade-off.
If somebody promises you an unusually high return with little or no risk, slow down.
You are allowed to ask questions.
You are allowed to walk away.
You are allowed to say:
“I do not understand this well enough to put my money into it.”
That sentence can save you a tremendous amount of grief.
So What Are Stocks?
Let’s keep this simple.
When you buy stock, you are buying a small ownership interest in a company.
If the company becomes more valuable, the value of the stock may rise.
Some companies also distribute part of their profits to shareholders through dividends.
The opposite can happen too.
Companies struggle.
Stock prices fall.
Businesses fail.
You can lose money.
That is one reason I do not want a beginning investor thinking:
“Which stock should I pick?”
as the first question.
There is a larger forest we need to see before we start choosing individual trees.
What Are Bonds?
A bond is different.
Instead of buying ownership, you are essentially lending money to an organization—such as a government or corporation—under agreed terms.
The borrower generally agrees to pay interest and return the principal according to the bond’s terms.
Bonds have risks too.
Their values can change.
Borrowers can run into trouble.
Interest-rate changes affect bond prices.
Again, you do not need to become an expert today.
You simply need to understand that stocks and bonds do different jobs and behave differently.
That difference becomes useful when we talk about diversification.
What Is a Mutual Fund?
Imagine that instead of buying one company, you put your money into a large pool with many other investors.
That pool then owns a collection of investments.
That is essentially what a mutual fund does.
Depending on the fund, it may own stocks, bonds, or other investments.
This makes it possible for someone with a relatively modest amount of money to own pieces of many investments rather than having to purchase each one individually.
What Is an ETF?
An exchange-traded fund, or ETF, is another pooled investment.
Like a mutual fund, an ETF can hold many different investments.
One practical difference is that ETFs trade on exchanges during the trading day much like individual stocks.
For our purposes here, the more important concept is not the technical distinction.
It is this:
Funds can make diversification much easier than trying to assemble dozens of individual investments yourself.
Diversification: Stop Betting Everything on One Thing
Diversification is one of the simplest ideas in investing.
Do not put everything in one place.
If all of your investment money is in one company and that company collapses, you have a serious problem.
If your money is spread across many companies, industries, types of investments, and perhaps different regions, the failure of one piece does not necessarily destroy the whole.
Diversification does not eliminate risk.
A diversified portfolio can still decline.
It simply reduces your dependence on the success of any single investment.
Think of it as financial redundancy.
As a former laboratory scientist, redundancy makes perfect sense to me.
You do not build an entire system that works only if one single component behaves perfectly forever.
Your investment life deserves the same consideration.
Seeing the Forest Before the Trees
Years ago, I wrote about investing using the phrase:
See the forest, then the trees.
I still like it.
The forest is your financial life.
What are you building?
What money will you need soon?
What money is available for the long term?
How much risk can you tolerate?
What accounts do you already have?
What are you trying to accomplish?
The trees are the individual investments.
Do not start with the trees.
Do not begin with:
“Should I buy Apple?”
“Should I buy gold?”
“Should I buy cryptocurrency?”
“My friend says this company is about to explode. Should I buy it?”
Those are tree questions.
First understand the forest.
Account and Investment Are Not the Same Thing
This causes enormous confusion.
An IRA is not an investment.
A 401(k) is not an investment.
A brokerage account is not an investment.
These are accounts or containers that can hold investments.
Inside the account you may own mutual funds, ETFs, stocks, bonds, cash, or other eligible assets.
Think of it this way:
The account is the bucket.
The investment is what you put inside the bucket.
This matters because people sometimes proudly tell me:
“I opened an IRA!”
Excellent.
Then I ask:
“What is the money invested in?”
And occasionally the answer is:
“I have no idea.”
Opening the bucket does not finish the job.
You need to know what is inside it.
Retirement Accounts Have Special Rules
Retirement accounts such as workplace plans and IRAs receive special tax treatment under federal rules.
Different account types have different rules about contributions, taxes, withdrawals, and eligibility.
You do not have to memorize those rules before beginning.
But you should understand what kind of account you have.
Ask:
Is this a traditional or Roth account?
Is there an employer match?
What am I contributing?
What am I actually invested in?
What fees am I paying?
When can I access the money?
Those five questions will put you ahead of a surprising number of people.
If Your Employer Matches Contributions, Learn How It Works
Many workplace retirement plans include some type of employer contribution or matching arrangement.
If yours does, understand it.
What percentage do you need to contribute?
Does the employer contribution vest immediately or over time?
What happens if you leave the company?
Do not assume.
Read the plan.
Ask questions.
Money offered through an employer benefit is part of your compensation.
Understand what you are receiving.
Then There Is the Brokerage Account
A regular taxable brokerage account is another kind of container for investments.
It does not have the same retirement-account restrictions, but it also does not receive the same tax treatment.
Why might someone use one?
Perhaps they have already funded retirement accounts and want to invest additional money.
Perhaps they are building assets for a goal that occurs before retirement.
Perhaps flexibility matters.
Again, the question is not:
“Is a brokerage account good?”
The question is:
“What job does this account have in my financial life?”
Fees Matter
Investment costs can look tiny.
One percent.
Half a percent.
A transaction charge here.
An advisory fee there.
Small numbers are easy to ignore.
But investing is a long-term process.
Small costs repeated year after year can meaningfully affect what you keep.
So ask:
What does this investment cost?
What does this account cost?
Am I paying an advisor?
What services am I receiving for that fee?
Are there additional fund expenses?
You do not need to choose the absolute cheapest thing available.
You do need to know what you are paying for.
Compounding Needs Time
One reason investing can become powerful is compounding.
Your money may earn a return.
Then future returns can be earned not only on the money you originally invested but also on earlier gains that remain invested.
The magic ingredient is not brilliance.
It is time.
That is one reason I keep telling people not to dismiss small contributions.
A person who begins steadily investing modest amounts and gives those investments years to work may be doing something far more valuable than someone who waits for the perfect moment to make one enormous investment.
Time matters.
Consistency matters.
Regular Investing Can Remove Some of the Drama
Markets move constantly.
If you wait until you are certain it is the “perfect” time to invest, you may be waiting for something that only becomes obvious afterward.
One approach people use is investing a consistent amount on a regular schedule.
That might mean contributing every paycheck or every month.
The point is not that this guarantees a particular result.
It does not.
The benefit is behavioral.
You create a system.
You stop requiring yourself to predict what the market will do next Tuesday.
You keep working the plan.
Do Not Invest Your Emergency Fund
Let us make this one wonderfully clear.
Your emergency savings has a job.
Its job is to be available when something goes wrong.
Do not become frustrated because that money is not producing spectacular investment returns.
That is not its assignment.
Remember our buckets.
Safety money protects.
Growth money grows.
Sometimes we make financial life unnecessarily complicated because we demand that every dollar perform every job simultaneously.
Let each bucket do its job.
Do Not Invest Money You Cannot Afford to Leave Alone
If you know you will need money soon, be very careful about putting it somewhere that may be down in value when you need it.
This is why time horizon matters so much.
Investing works best when you have enough flexibility to allow the plan time to operate.
You do not want to be forced to sell something simply because an unexpected expense arrived.
Which brings us right back to the financial floor.
Emergency savings protects your investment plan too.
Beware of Excitement
Excitement and investing are not always excellent companions.
The hot stock.
The secret opportunity.
The thing everyone on social media suddenly appears to own.
The investment that your cousin’s neighbor’s barber says cannot lose.
Slow down.
The more urgently somebody needs you to invest before you understand what you are doing, the more carefully I want you to proceed.
You do not have to invest in everything.
In fact, one of the most useful financial skills is becoming comfortable saying:
“No, thank you. I don’t understand that investment.”
There will be other opportunities.
You Don’t Need to Beat Everybody
Another strange thing happens once people start investing.
Suddenly it becomes competitive.
“My portfolio earned this.”
“You only earned that?”
“This stock doubled.”
“I bought before everybody else.”
Stop.
Your job is not to win investing.
Your job is to use investing as one tool for building the financial life you want.
You do not need the highest return at the dinner table.
You need a plan appropriate to your goals, time horizon, resources, and ability to tolerate risk.
Comparison can push otherwise sensible people into decisions they do not understand.
Stay on your own ship.
What About a Financial Advisor?
There is absolutely nothing wrong with getting professional help.
Some people enjoy managing investments themselves.
Others would rather have professional guidance.
Either is fine.
But hiring someone does not mean handing over responsibility for understanding what is happening.
Ask questions.
How are you compensated?
What services are included?
What investments are you recommending?
Why?
What are the fees?
What are the risks?
Are you registered?
What happens if I want to leave?
Can you explain this to me without jargon?
That last question matters to me.
If someone cannot explain an investment in language you can understand, you are not obligated to buy it.
Your money does not become less yours simply because a professional is involved.
Learn Enough to Participate
You do not need a finance degree.
You do need enough understanding to participate in conversations about your own money.
Learn the vocabulary gradually.
Today you understand the difference between saving and investing.
Then stocks and bonds.
Then funds.
Then accounts.
Then diversification.
Eventually these words stop sounding intimidating.
That is how expertise begins.
One understandable concept at a time.
Where Do I Start?
If you are sitting there thinking:
“Fine, Janine. What do I actually do Monday morning?”
Here is where I would begin.
First, make sure you understand your financial floor.
Do you have some emergency savings?
Are you managing high-interest debt?
Do you know what you need this money for?
Then look at what is already available to you.
Do you have a retirement plan through work?
Do you have an IRA?
Do you know what is inside those accounts?
Are contributions happening automatically?
Are you receiving an employer match if one is available?
Then learn.
Pick one account.
Open the statement.
Figure out what you own.
Look up the words you do not understand.
Ask questions.
That alone is progress.
You Are Not Behind Because You Are Learning
This is especially important for the person who begins investing later than they wish they had.
Yes, starting earlier gives money more time.
But you cannot invest yesterday.
You can only make a decision with the resources you have today.
Do not waste another five years feeling embarrassed that you did not begin ten years ago.
Start learning now.
Start contributing now.
Make the best decisions you can now.
Then keep going.
Investing Is One Part of the Financial Floor
I do not want investing to become the new obsession.
Investing is not the whole financial plan.
It sits beside:
savings,
debt reduction,
income,
insurance,
retirement planning,
creation,
giving,
and the everyday life you are actually living.
Harmony.
That is the point.
You are building several kinds of strength at the same time.
The Goal Is Not to Become an Investor
Technically, yes, you may become one.
But that is not the larger goal.
The goal is to create a financial life in which some of your money is working toward the future without requiring every future dollar to come from another hour of your labor.
You are gradually building resources.
Assets.
Options.
Time.
Choice.
You do not need to rush into the market because everybody else seems to know what they are doing.
Learn.
Ask questions.
Understand the forest.
Then choose the trees.
That is enough.
Read Next
Know What Your Money Is For
Intentional spending becomes much easier once you know what you want your money to help you build.
The 60/40 Principle of Money Management
Give your money more than one job by supporting your present life while deliberately building financial stability for tomorrow.
Continue the Journey
This article is part of Revenue Without Rush — Level 1: Financial Footing.
Level 1 is about learning to direct your money deliberately—reducing debt, building savings, understanding your spending, and creating a financial floor strong enough to support what comes next.
[Explore Revenue Without Rush →]
This material is educational and is not individualized financial, investment, tax, or legal advice.